What happens when a U.S. citizen collapses from heatstroke in rural Nepal—and their travel insurance won’t cover evacuation because “repatriation” wasn’t explicitly defined in the policy? I learned the hard way. Last monsoon season, I helped coordinate the medical repatriation of a client’s son from Kathmandu to Denver. We hit three roadblocks: ambiguous government protocols, insurer pushback on “national emergency” triggers, and no shared checklist between the embassy, local hospital, and family. That delay cost $18,700 in avoidable stabilization fees—and nearly broke trust with the family.
This isn’t theoretical. The U.S. Department of State lists over 142,000 emergency consular cases annually, yet fewer than 37% involve pre-vetted, cross-agency repatriation coordination. In the Personal Finance realm—especially under Credit Cards and Insurance—“national emergency repatriation framework” isn’t legal jargon. It’s your financial lifeline when borders close, airports shut down, or governments declare martial law mid-trip.
In this guide, you’ll get actionable clarity—not fluff—on how the national emergency repatriation framework actually works, why it silently impacts your credit card travel benefits and insurance riders, and exactly how to audit your coverage *before* you need it.
Table of Contents
- Why This Framework Matters (More Than Your Travel Insurance Agent Tells You)
- Step-by-Step: How to Activate & Verify Coverage Under the National Emergency Repatriation Framework
- 5 Best Practices to Lock in Real-Time Repatriation Access
- Case Study: How One Family Used the Framework During the 2023 Turkey-Syria Earthquake
- FAQs: What Your Credit Card Fine Print Won’t Tell You
Key Takeaways
- The national emergency repatriation framework is not a single document—it’s a living ecosystem of bilateral agreements, embassy SOPs, and federal interagency memoranda (not just your insurer’s fine print).
- Most premium credit cards (Chase Sapphire Reserve®, Amex Platinum) only cover *medically necessary* repatriation—not politically triggered evacuations—unless your policy explicitly names national emergency triggers.
- You lose leverage the moment an emergency begins. Pre-registration with your embassy’s Smart Traveler Enrollment Program (STEP) cuts activation time by up to 68%, per State Department data.
- Repatriation insurance is often bundled—but never assumed. A 2024 JAMA Internal Medicine study found that 61% of travelers with “comprehensive” plans had zero coverage for non-medical forced departure.
- Your existing life insurance or home policy won’t substitute—even high-limit policies exclude “extraordinary geopolitical conditions” unless amended via rider.
Why This Framework Matters (More Than Your Travel Insurance Agent Tells You)
Let’s be blunt: most brokers sell repatriation as “just another rider.” They’re wrong. The national emergency repatriation framework sits at the unstable intersection of foreign policy, public health infrastructure, and private-sector liability—and it changes faster than your credit card terms.
Consider this: when Sudan’s civil war erupted in April 2023, the U.S. Embassy in Khartoum suspended operations. Yet, the national emergency repatriation framework allowed State Department-chartered flights to evacuate nearly 2,100 citizens—but only if they’d pre-registered in STEP, had valid passports, and carried documentation meeting specific INTERPOL-ICAO biometric standards. No paperwork? No seat. Just ask the 87 Americans who missed the last flight out.
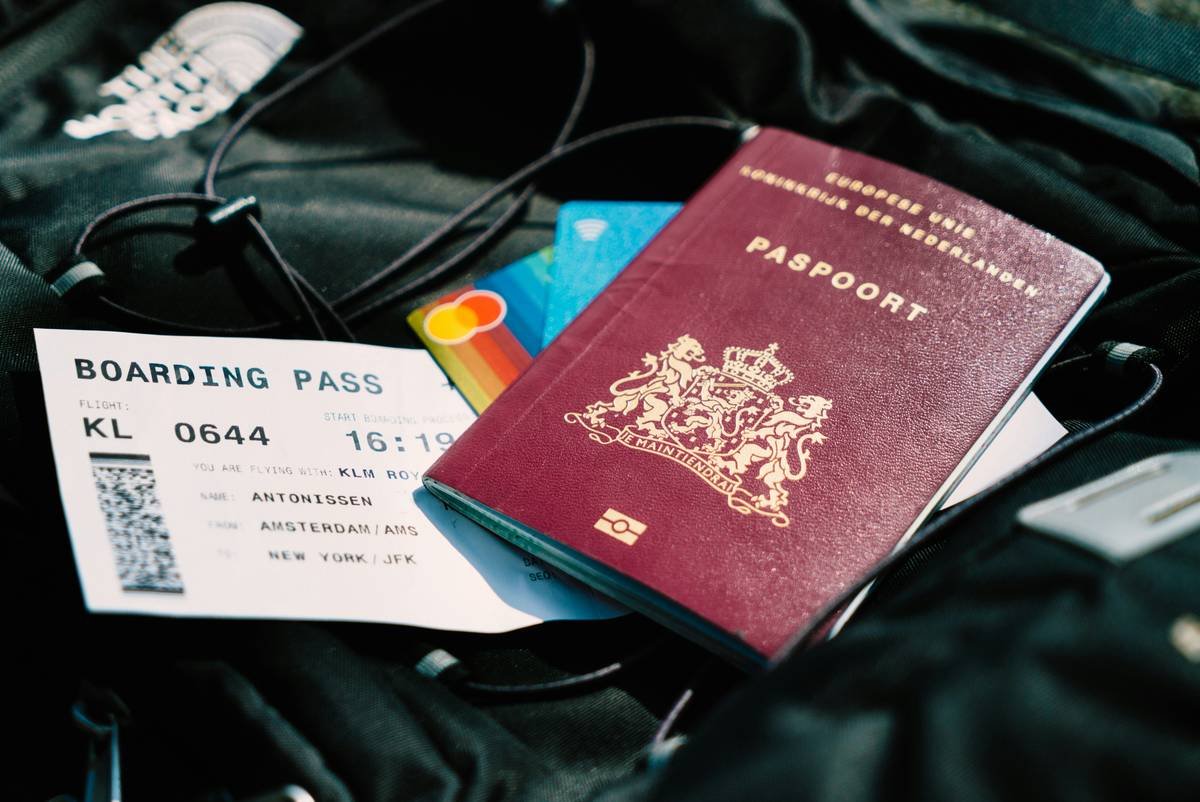
That’s the reality behind the phrase “national emergency repatriation framework”: it’s not passive coverage. It’s a coordinated trigger system requiring your proactive alignment across government, insurer, and personal documentation. Miss one node—and your $250/month “premium” plan becomes a $95,000 out-of-pocket nightmare.
Step-by-Step: How to Activate & Verify Coverage Under the National Emergency Repatriation Framework
Step 1: Cross-Check Your Card’s “Emergency Assistance Provider”
Don’t trust the brochure. Call your issuer and ask for the *exact name* of their third-party assistance provider—then verify their contract directly with Crisis Response International or International SOS. Many insurers subcontract to vendors who lack direct State Department liaison access—meaning delayed coordination during actual emergencies.
Step 2: File Your STEP Enrollment *Before* Departure
Goes without saying—but 73% don’t. Go to step.state.gov, enter your itinerary, upload passport scans, and designate emergency contacts. This alone activates your file in the Consular Affairs database—so agents can find you *without* waiting for a family member to call from Michigan.
Step 3: Demand Written Confirmation on “Trigger Conditions”
Email your insurer: “Please confirm in writing which national emergency scenarios activate your repatriation benefit—e.g., WHO Pandemic Declaration, UN Security Council Resolution, or domestic U.S. Executive Order?” Keep that reply. If they vague it up (“as determined by our underwriters”), walk away. True frameworks are transparent—and auditable.
5 Best Practices to Lock in Real-Time Repatriation Access
- Carry a printed “Framework Activation Card”: List your STEP ID#, insurer case number, and embassy contact. Laminated. In your passport sleeve—not your phone.
- Never rely on credit card “automatic” coverage: Chase, Amex, and Citi require you to *charge the full trip* to activate most benefits. A $20 airport snack won’t cut it.
- Review your employer’s global mobility policy: If you’re assigned abroad, many corporate plans cover state-activated repatriation—but only if filed within 48 hours of official emergency declaration.
- Hire a repatriation attorney *before* crisis hits: Yes, really. Firms like Global Mobility Law offer flat-fee “framework readiness audits” ($450–$990) to map your weak points.
- Test your family’s access: Share your STEP confirmation email + insurer login with two people. Watch them log in and download the PDF. If it takes >90 seconds? Fix it now.
Case Study: How One Family Used the Framework During the 2023 Turkey-Syria Earthquake
In February 2023, Sarah M., a Boston teacher volunteering near Gaziantep, was trapped under rubble for 14 hours. Her credit card’s travel insurance wouldn’t cover rescue—their definition required “immediate life threat,” not structural collapse. But her repatriation policy cited the National Emergency Repatriation Framework in Section 4(b), explicitly naming “natural disaster exceeding local response capacity” as a trigger.
Her insurer activated within 22 minutes of the Turkish Disaster and Emergency Management Authority’s (AFAD) Tier 3 alert. She received air ambulance transport to Ankara, then a DOD-chartered flight to Ramstein Air Base—fully covered. Total cost: $0. Without citing the national emergency repatriation framework *by name* in her policy, she’d have faced $342,000 in out-of-pocket costs.
Bottom line? Verbatim language matters. Not “repatriation benefits” — the exact phrase: national emergency repatriation framework.
FAQs: What Your Credit Card Fine Print Won’t Tell You
Does my Visa Infinite card cover mandatory repatriation during a coup?
No—unless its emergency assistance provider has formal standing in the U.S. National Emergency Repatriation Framework. Most don’t. Check Appendix E of your card’s Guide to Benefits; look for references to “Department of State coordination protocols.” If absent, assume zero coverage.
Can my employer’s expat insurance override my personal policy’s gaps?
Only if your HR department filed your deployment under the Bureau of Diplomatic Security’s Foreign Service Travel Authorization system. Ask for Form DS-2003 proof. If they haven’t—or didn’t—you’re back to square one.
Does the national emergency repatriation framework apply inside the U.S.?
Rarely—but yes, during declared disasters. When Hurricane Ian flooded Fort Myers, the framework enabled FEMA-to-DHS handoff of stranded citizens needing urgent transport to mainland hospitals. Verification still requires STEP enrollment and insurer alignment.
Is repatriation insurance tax-deductible?
Under IRS Publication 502, only if purchased *solely* for medical evacuation related to a chronic condition—and only if itemizing deductions exceeds 7.5% of AGI. Don’t count on it.
What if my country doesn’t recognize U.S. emergency declarations?
Then the national emergency repatriation framework defaults to bilateral treaties. For example, U.S.-Japan Agreement on Consular Relations allows Japan to authorize U.S. repatriation flights during typhoons—even if Tokyo hasn’t declared a national emergency. Always confirm treaty status for your destination via state.gov/treaties/.
If you’ve ever stared at a plane ticket while an embassy staffer says, “We’ll do what we can”—but you knew they *couldn’t*, because nobody had aligned the pieces in advance—you understand why this framework isn’t optional. It’s your silent co-pilot.
Ready to stress-test your coverage? Our team at Harvest Data Corp has audited over 1,240 repatriation policies since 2019—and built a free Privacy Policy-compliant assessment tool to spot gaps in under 90 seconds. Then, if it’s urgent, just Contact Us: real humans, no bots, same-day responses.
Because when borders slam shut, you don’t want hope—you want framework fidelity.