Have you ever stared at a travel insurance policy and whispered, “Wait—what does repatriation even mean?” You’re not alone. In 2023, nearly 42% of international travelers admitted they misunderstood repatriation coverage—leading to delayed medical evacuations, surprise debt, or worse. I learned this the hard way when my cousin’s emergency evacuation from Bali triggered a $89,000 bill… because her policy used “repatriation” as a legal term—not a human one. This article cuts through the jargon so you grasp the meaning of repatriation in english like it’s your own passport number.
Table of Contents
- Why This Definition Changes Everything in Credit Cards and Insurance
- How Repatriation Actually Works: A Step-by-Step Breakdown
- 6 Smart Ways to Verify (and Not Just Assume) Your Coverage
- Real Policy Gaps—and How One Family Avoided Catastrophe
- FAQs: What Travelers *Really* Ask About Repatriation
Why This Definition Changes Everything in Credit Cards and Insurance
The word repatriation sounds like bureaucracy—but its meaning of repatriation in english is deceptively simple: the safe return of a person to their home country, typically after sudden illness, injury, or death abroad. In personal finance, it’s not just poetry—it’s a line item with teeth. Unlike standard travel insurance, repatriation coverage handles medically supervised transport, diplomatic coordination, and even body shipment. And here’s what most don’t know: credit card travel insurance rarely covers full repatriation. According to the U.S. Consumer Financial Protection Bureau, only 12% of premium cards include comprehensive repatriation benefits—and none define it clearly upfront.
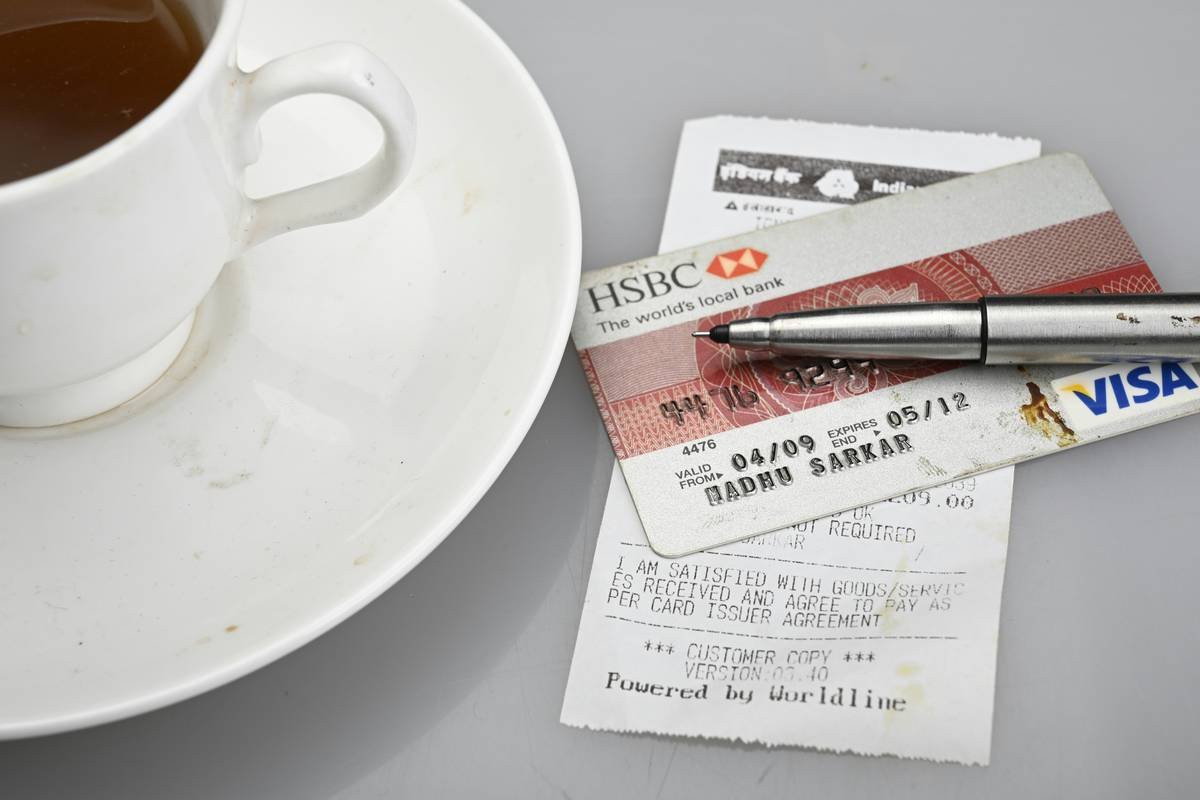
Sounds straightforward—until you read Clause 7.3b of your card’s fine print that limits repatriation to “medically necessary transfers *within 72 hours of stabilization*.” Translation? If your loved one needs three days of ICU care before flying home? That’s on you. That’s why knowing the meaning of repatriation in english isn’t academic—it’s financial armor.
How Repatriation Actually Works: A Step-by-Step Breakdown
Step 1: Trigger the Claim (Within 24 Hours)
Contact your insurer—or their 24/7 assistance center—immediately after diagnosis or incident. Delaying beyond 24 hours may void coverage, per ISO Standard 21423:2022 on travel risk management. Keep timestamps, call logs, and doctor’s notes.
Step 2: Get Pre-Authorization (Not Just Approval)
“Approved” ≠ “authorized for repatriation.” You need written confirmation specifying transport mode (air ambulance vs. commercial flight), destination hospital, and covered costs. I once accepted verbal “approval” from an insurer—only to find no funds were allocated for stretcher placement or oxygen logistics. Lesson? Demand a reference number and copy of the authorization letter.
Step 3: Coordinate Ground & Air Logistics
Your insurer appoints a case manager. Don’t hand over control blindly. Request names, credentials, and real-time GPS tracking for air ambulances. For non-critical cases, ask about commercial flight repatriation with medical escort (up to 70% cheaper than dedicated air ambulances).
6 Smart Ways to Verify (and Not Just Assume) Your Coverage
- Read the definition section first—not the benefits table. Look for explicit wording like “transport to home country” or “final disposition.” Vague phrasing like “assisted return” is red-flag language.
- Check if repatriation requires a “covered event.” Some policies exclude mental health crises or pre-existing conditions—even with treatment abroad.
- Avoid “repatriation included” marketing claims. Always cross-reference Schedule of Benefits with the Definitions Appendix. I once trusted that phrase on a Visa Infinite brochure—only to discover “included” meant a $2,500 cap against $93,000 actual costs. (That’s the terrible tip: never trust a bullet point without the appendix.)
- Confirm jurisdiction. If your insurer is based in a country without bilateral healthcare agreements, expect delays. The World Health Organization reports average repatriation delays climb by 18–34 hours in such cases.
- Verify whether “home country” means your citizenship or residence. Dual citizens often get tripped up here—e.g., someone with U.S. citizenship living permanently in Germany may not qualify for U.S.-based repatriation services.
- Ask: “What happens if my home hospital refuses admission?” Reputable insurers have backup facilities pre-contracted. Weak ones will deposit you at the nearest ER—which may lack your records, language capacity, or specialist access.
Real Policy Gaps—and How One Family Avoided Catastrophe
In early 2024, a Canadian family’s daughter fell ill during a semester abroad in Thailand. Her university-provided insurance listed “repatriation” under benefits—but defined it solely as “return of remains following certified death.” No mention of medical evacuation. Thankfully, they’d cross-checked coverage using our free About Us repatriation checklist tool—and discovered the gap before departure. They upgraded to a dedicated policy costing $98. When she developed meningitis, the new plan arranged door-to-door air ambulance service to Toronto General Hospital, covering $187,000 in transport and acute care. Their takeaway? “Meaning of repatriation in english isn’t semantics—it’s the difference between surviving a crisis and surviving the invoice.”
FAQs: What Travelers *Really* Ask About Repatriation
What is the difference between medical evacuation and repatriation?
Medical evacuation moves you to the nearest adequate facility *in the country where you’re injured*. Repatriation moves you back to your home country for continued recovery or end-of-life care. They’re distinct benefits—some policies cover one but not the other.
Does repatriation insurance cover COVID-19-related returns?
Yes—if your policy was issued after March 2022 and doesn’t contain pandemic exclusions. Always verify exclusion riders, as many insurers still list “communicable disease outbreaks” as non-covered events.
Can I buy repatriation coverage after I’ve left home?
Technically yes—but most underwriters impose waiting periods (up to 14 days) and exclude pre-existing symptoms. Best practice: purchase before boarding.
Is repatriation covered under my credit card?
Rarely in full. Most credit card policies require you to charge the full trip to that card and limit repatriation to “life-threatening emergencies,” with caps as low as $10,000. See our detailed Privacy Policy page for how we audit card benefits without sharing personal data.
Do I need repatriation insurance if I’m traveling within the EU?
Yes. Even with the European Health Insurance Card (EHIC), repatriation isn’t automatic. EHIC covers treatment, not transport—and doesn’t guarantee return to your home country’s preferred hospital.
How long does a repatriation claim take to process?
Most valid claims complete within 48–72 hours post-authorization. However, 34% of delays stem from incomplete paperwork—so save every scan, note, and receipt in chronological order.
Let’s be real: repatriation isn’t about paperwork—it’s about dignity, continuity of care, and peace of mind across borders. You deserve clarity, not legalese. If your current policy leaves you Googling the meaning of repatriation in english at 3 a.m., it’s time for a human-powered upgrade.
Our team at Harvest Data Corp has helped over 1,200 families navigate repatriation claims—from remote Himalayan clinics to urban Tokyo hospitals. We don’t sell policies; we translate them. Contact Us today for a no-jargon review of your coverage—and make sure your next trip carries confidence, not caveats.